

Introduction
Owning rental property in California can be rewarding, but it also comes with financial risks that every property owner should prepare for. Unexpected events such as fires, storms, vandalism, lawsuits, or temporary rental income loss can quickly become expensive. Having the right landlord insurance California policy helps protect your investment and gives you greater financial confidence.
Many new landlords assume their homeowners insurance will continue protecting a property after it becomes a rental. In most situations, that is not the case. Rental properties have different risks, and they often require insurance specifically designed for landlords.
Whether you own a single-family rental home, a duplex, a condominium, or several investment properties, understanding your insurance options can help you make better decisions and avoid costly mistakes.
This guide explains how landlord insurance works, what it usually covers, what affects its cost, California legal considerations, and 7 smart owner tips that can help you protect your rental property while keeping insurance costs under control.
Quick Answer
Landlord insurance California is designed for people who rent residential property to tenants. It generally helps protect the rental building, landlord-owned property, liability risks, and rental income after certain covered events.
Depending on your policy, coverage may include:
- Dwelling protection
- Other structures coverage
- Landlord personal property
- Personal liability coverage
- Loss of rental income
- Optional endorsements for additional protection
Every insurance company offers different policy options, so comparing coverage before buying is important.
Key Facts About Landlord Insurance California
| Feature | Details |
| Designed For | Rental property owners |
| Covers Building | ✔ Yes |
| Covers Tenant Belongings | ✘ No |
| Liability Protection | ✔ Yes |
| Rental Income Protection | Usually Included |
| Flood Insurance | Separate Policy |
| Earthquake Coverage | Optional |
| Required by California Law | No |
| Best For | Houses, condos, duplexes, apartment buildings |
What Is Landlord Insurance?
Landlord insurance is a policy created specifically for rental property owners. Unlike homeowners insurance, it focuses on protecting property that is rented to tenants rather than occupied by the owner.
Rental properties face different risks than primary residences. A tenant injury, accidental fire, vandalism, or a severe storm could lead to expensive repairs or legal claims. Landlord insurance helps reduce the financial impact of these unexpected events.
While coverage varies by insurer, most policies combine property protection with liability coverage, giving landlords broader financial security.
Why Homeowners Insurance May Not Be Enough
One of the most common mistakes new landlords make is keeping a homeowners policy after converting a house into a rental property.
Because homeowners insurance is intended for owner-occupied homes, it may not provide the protection needed once tenants move in.
Here is a simple comparison.
| Homeowners Insurance | Landlord Insurance |
| Owner lives in the home | Property is rented to tenants |
| Covers personal belongings | Covers landlord-owned property only |
| Limited rental protection | Designed for rental risks |
| No rental income coverage | May include loss of rental income |
| Standard liability | Liability designed for rental properties |
Updating your insurance when a property becomes a rental can help avoid unexpected coverage gaps.
Who Should Buy Landlord Insurance in California?
If you earn income from residential rental property, landlord insurance is generally worth considering.
It can be suitable for:
- Single-family rental homeowners
- Duplex owners
- Triplex owners
- Fourplex investors
- Condominium landlords
- Townhouse landlords
- Apartment building owners
- Vacation rental owners (with appropriate coverage)
- Real estate investors with multiple rental properties
Even if you rent out only one property, protecting that investment can help reduce financial risk over time.
Rental Properties Commonly Covered
Insurance companies offer policies for many different types of rental properties.
| Rental Property | Commonly Covered |
| Single-family home | ✔ |
| Duplex | ✔ |
| Triplex | ✔ |
| Fourplex | ✔ |
| Condominium | ✔ |
| Townhouse | ✔ |
| Apartment building | Usually |
| Seasonal rental | Depends on insurer |
| Short-term rental | Special policy may be needed |
Always confirm eligibility with your insurance provider because coverage options can vary.
What Does Landlord Insurance California Usually Cover?
Although every policy is different, most landlord insurance plans include several important types of protection.
These commonly include:
- Coverage for the rental building
- Detached structures
- Landlord-owned personal property
- Liability protection
- Loss of rental income after covered damage
Understanding each coverage type makes it easier to compare policies and choose protection that fits your property.
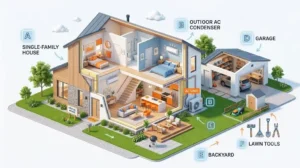
H3Dwelling Coverage
Dwelling coverage protects the physical structure of the rental property.
Covered events often include:
- Fire
- Lightning
- Windstorms
- Smoke damage
- Hail
- Certain acts of vandalism
If a covered event damages your rental property, this coverage can help pay for repairs or rebuilding costs up to your policy limits.
H3: Other Structures Coverage
Many rental properties include detached buildings or outdoor structures.
Examples include:
- Detached garages
- Storage sheds
- Fences
- Gates
- Workshops
- Detached guest units
If these structures are damaged by a covered event, your policy may help pay for repairs.
H3: Landlord Personal Property Coverage
Landlords often own items used to maintain or furnish the rental property.
Examples include:
- Lawn equipment
- Maintenance tools
- Appliances provided with the rental
- Cleaning supplies
- Furnished rental furniture
If these items are damaged by a covered event, landlord insurance may help cover replacement costs.
H3: Personal Liability Protection
Liability coverage is one of the most valuable parts of landlord insurance.
If someone is injured on your rental property and you are found legally responsible, liability coverage may help pay for:
- Medical expenses
- Legal defense costs
- Court judgments
- Settlement costs
This protection can help safeguard your finances against unexpected liability claims.
H3: Loss of Rental Income Coverage
Sometimes a covered event makes a rental property temporarily unlivable.
If that happens, many landlord insurance policies help replace lost rental income while covered repairs are completed.
This feature can be especially helpful for landlords who rely on monthly rental payments as part of their income.
H2: 7 Smart Owner Tips to Choose Better Landlord Insurance California
Selecting the right policy is about more than finding the lowest premium. A cheaper policy may leave important gaps in coverage that could cost far more after a claim.
The following tips can help California landlords make smarter insurance decisions.
H3: Tip 1: Insure Your Home for Its Rebuilding Cost
Choose coverage based on rebuilding costs rather than the property’s market value. Construction costs can rise quickly, especially after major disasters.
H3: Tip 2: Review Your Liability Limits Carefully
Higher liability limits may provide better financial protection if a serious injury or lawsuit occurs on your rental property.
H3: Tip 3: Ask About Wildfire Protection
Many parts of California face wildfire risks. Review your policy carefully to understand how wildfire damage is covered and whether additional protection is available.
H2: What Is Usually Not Covered by Landlord Insurance?
Knowing what your policy does not cover is just as important as knowing what it does cover. Many landlords assume every type of damage is automatically included, but most insurance policies have exclusions and coverage limits.
Reviewing these exclusions before purchasing a policy can help you avoid unexpected expenses later.
| Common Exclusion | Typical Coverage Status | Possible Solution |
| Tenant’s personal belongings |  Not Covered |
Tenant purchases renters insurance |
| Flood damage | Usually Excluded |
Buy a separate flood insurance policy |
| Earthquake damage | Usually Excluded |
Add earthquake coverage |
| Normal wear and tear | Not Covered |
Regular property maintenance |
| Pest or insect damage | Not Covered |
Preventive maintenance |
| Intentional damage by the landlord | Not Covered |
Not insurable |
| Vacant property for long periods | Depends on policy | Ask about vacant property coverage |
Understanding these limitations helps you choose optional protections that fit your property’s needs.
H2: Optional Coverage That May Be Worth Considering
Every rental property is different. Depending on your property’s location, value, and rental type, optional endorsements may provide additional financial protection.
Some of the most common options include:
H3: Earthquake Coverage
California experiences frequent seismic activity, but earthquake damage is generally not included in a standard landlord insurance policy.
If your rental property is located in an area with higher earthquake risk, adding this coverage may be worth considering.
H3: Flood Insurance
Flood damage is another major exclusion from most standard landlord insurance policies.
Properties located near rivers, lakes, coastal areas, or regions with heavy rainfall may benefit from a separate flood insurance policy.
H3: Equipment Breakdown Coverage
Modern rental homes often include expensive systems such as:
- HVAC units
- Water heaters
- Electrical systems
- Appliances
Equipment breakdown coverage may help pay for sudden mechanical or electrical failures that are not caused by normal wear and tear.
H3: Building Code Upgrade Coverage
Construction standards change over time.
If your rental property is damaged and local building codes require upgrades during repairs, this optional coverage may help pay those additional costs.
H3: Extended Replacement Cost Coverage
Construction costs can increase unexpectedly after major disasters.
Extended replacement cost coverage may provide additional protection if rebuilding costs exceed your dwelling coverage limit.
H2: Factors That Affect Landlord Insurance California Costs
No two landlords pay exactly the same premium. Insurance companies evaluate several factors before calculating the price of a policy.
The following table highlights the most common pricing factors.
| Factor | Impact on Premium |
| Property location | High |
| Wildfire exposure | High |
| Age of the building | Medium to High |
| Construction materials | Medium |
| Replacement cost | High |
| Coverage limits | High |
| Deductible amount | Medium |
| Claims history | High |
| Credit-based insurance score (where permitted) | Medium |
| Security features | May reduce premium |
H3: Property Location
Location is one of the biggest pricing factors.
Homes in areas with higher wildfire risk, severe weather, or increased crime may have higher insurance premiums than similar properties in lower-risk areas.
H3: Property Age and Condition
Older homes often cost more to insure because they may have:
- Older electrical systems
- Aging plumbing
- Roof deterioration
- Higher repair costs
Updating these systems may help lower insurance costs.
H3: Coverage Limits
Choosing higher policy limits increases financial protection but can also increase your premium.
The goal is to select limits that adequately protect your investment without paying for unnecessary coverage.
H3: Deductible Selection
A deductible is the amount you pay before insurance begins covering a claim.
| Lower Deductible | Higher Deductible |
| Higher premium | Lower premium |
| Lower out-of-pocket after a claim | Higher out-of-pocket after a claim |
| Better for frequent small claims | Better for larger emergency savings |
Choose a deductible that fits your financial situation.
H2: Estimated Cost of Landlord Insurance in California
Insurance premiums vary widely depending on the property’s characteristics and the coverage selected.
Typical pricing is influenced by:
- Property size
- Replacement value
- Location
- Claims history
- Deductible
- Optional endorsements
- Insurance company
The following ranges are general estimates only.
| Property Type | Estimated Annual Premium* |
| Small rental home | $900–$1,600 |
| Single-family rental | $1,000–$2,200 |
| Duplex | $1,500–$3,000 |
| Triplex or Fourplex | $2,000–$4,500+ |
*Actual premiums vary by insurer, location, coverage limits, deductible, and underwriting guidelines.
H2: California Laws Every Landlord Should Understand
Although California generally does not require landlords to carry landlord insurance, property owners must comply with various laws that affect rental housing.
Insurance protects your finances, while legal compliance helps reduce disputes with tenants.
H3: Habitability Requirements
California landlords are generally responsible for maintaining safe and livable rental housing.
This includes addressing issues involving:
- Plumbing
- Heating
- Electrical systems
- Structural safety
- Water supply
- Weather protection
Keeping the property in good condition may also help reduce insurance claims.
H3: Security Deposit Rules
California has rules regarding how security deposits are collected, used, and returned.
Keeping detailed inspection records and photographs before and after each tenancy can help resolve disputes if property damage occurs.
H3: Property Entry Requirements
Landlords generally cannot enter an occupied rental property whenever they choose.
Except in certain emergency situations, advance notice is typically required before entering the property.
Understanding these rules helps maintain positive landlord-tenant relationships.
H3: Local Rent Regulations
Some California cities have rent stabilization or local housing regulations that may affect rental property management.
Before purchasing insurance, it is also wise to understand any local requirements that could influence your property’s risk profile or operating costs.
H2: How to Choose the Right Landlord Insurance Policy
Buying landlord insurance should involve more than comparing prices.
Use this checklist before making a decision.
| ✔ Checklist | Why It Matters |
| Compare multiple insurance companies | Better pricing and coverage options |
| Review exclusions carefully | Avoid unexpected surprises |
| Verify replacement cost limits | Helps protect rebuilding costs |
| Understand liability coverage | Reduces financial risk |
| Ask about available discounts | May lower premiums |
| Review deductible options | Balance premium and out-of-pocket costs |
| Update coverage annually | Keeps protection aligned with property value |
Choosing the right policy today can help prevent costly gaps in coverage tomorrow.
H2: Practical Ways to Save Money on Landlord Insurance California
Protecting your rental property does not always mean paying the highest premium. Many insurance companies offer discounts or pricing options that can help lower your costs while maintaining solid coverage.
Here are some practical ways to save.
H3: 1. Compare Quotes from Multiple Insurance Companies
Insurance companies calculate risk differently, so premiums for the same property can vary.
Before purchasing a policy:
- Request several quotes.
- Compare coverage, not just price.
- Review deductibles and policy limits.
- Check customer service and claims satisfaction.
A little extra research may help you find better value.
H3: 2. Bundle Insurance Policies
If you own multiple insurance policies, ask whether bundling is available.
You may qualify for discounts by combining:
- Landlord insurance
- Auto insurance
- Homeowners insurance
- Umbrella insurance
Bundling can simplify policy management while reducing overall insurance costs.
H3: 3. Increase Your Deductible Carefully
Choosing a higher deductible often lowers your annual premium.
However, make sure you have enough emergency savings to cover the deductible if you need to file a claim.
H3: 4. Improve Property Safety
Insurance companies often reward lower-risk properties.
Safety improvements may include:
- Smoke detectors
- Carbon monoxide detectors
- Deadbolt locks
- Security cameras
- Fire extinguishers
- Monitored alarm systems
These upgrades may reduce both insurance risk and property damage.
H3: 5. Maintain Your Property Regularly
Routine maintenance helps prevent larger problems.
Focus on:
- Roof inspections
- Plumbing maintenance
- Electrical system checks
- Tree trimming
- Gutter cleaning
- Exterior repairs
A well-maintained property is less likely to experience costly insurance claims.
H2: Common Mistakes California Landlords Should Avoid
Many insurance problems occur because landlords misunderstand their policy or delay updating coverage.
Avoid these common mistakes.
| Mistake | Why It Can Be Costly |
| Keeping a homeowners policy after renting the property | May create coverage gaps |
| Choosing the lowest premium only | Important protections may be missing |
| Ignoring policy exclusions | Unexpected claim denials |
| Underinsuring the property | Higher out-of-pocket rebuilding costs |
| Forgetting to update coverage after renovations | Improvements may not be fully protected |
| Skipping annual policy reviews | Coverage may become outdated |
Reviewing your policy every year can help ensure it still meets your property’s needs.
H2: Landlord Insurance vs. Renters Insurance
Many first-time landlords confuse landlord insurance with renters insurance.
Although both relate to rental properties, they protect different people and different types of property.
| Feature | Landlord Insurance | Renters Insurance |
| Protects the building | ✔ | ✘ |
| Covers tenant belongings | ✘ | ✔ |
| Covers landlord liability | ✔ | ✘ |
| Covers tenant personal liability | ✘ | ✔ |
| Covers landlord-owned appliances | ✔ | ✘ |
| Purchased by | Property owner | Tenant |
Encouraging tenants to purchase renters insurance can help reduce disputes after property damage or theft because it protects their personal belongings.
H2: Frequently Asked Questions (FAQs)
H3: Is landlord insurance required in California?
No. California generally does not require landlords to purchase landlord insurance. However, many lenders may require coverage for financed rental properties, and insurance is strongly recommended to help protect your investment.
H3: Does landlord insurance cover tenant damage?
It depends on the cause of the damage and the policy terms.
Accidental damage resulting from a covered event may be covered, while intentional damage caused by tenants is often excluded or subject to specific policy conditions. Always review your policy details.
H3: Does landlord insurance include earthquake coverage?
In most cases, no. Earthquake coverage is typically offered as an optional endorsement or a separate policy.
H3: Is flood damage covered?
Standard landlord insurance policies generally do not cover flood damage. A separate flood insurance policy is usually needed for that protection.
H3: Can I insure more than one rental property under the same company?
Yes. Many insurance companies offer coverage for multiple rental properties, and some may provide discounts for insuring more than one property with them.
H3: Should tenants have renters insurance?
While it may not always be legally required, many landlords encourage or require tenants to carry renters insurance. It helps protect the tenant’s personal belongings and may reduce disputes after covered losses.
H2: Key Takeaways
- Landlord insurance California is designed specifically for rental property owners.
- It commonly includes dwelling coverage, liability protection, landlord-owned property coverage, and loss of rental income after covered events.
- Standard policies usually do not include flood or earthquake coverage, but these protections may be available separately.
- Insurance premiums depend on factors such as property location, replacement cost, deductible, claims history, and selected coverage limits.
- Comparing policies, reviewing exclusions, and updating coverage regularly can help protect your investment and avoid costly surprises.
- Routine maintenance and property safety improvements may also help reduce insurance costs over time.
H2: Conclusion
Owning rental property is a long-term investment, and protecting that investment should be part of every landlord’s financial strategy. The right landlord insurance California policy can provide valuable protection against property damage, liability claims, and temporary loss of rental income after covered events.
Instead of choosing a policy based only on price, take time to compare coverage options, understand exclusions, and consider optional protections that fit your property’s location and risk profile. A thoughtful insurance decision today can help reduce financial stress and support the long-term success of your rental property.